Chemical Market Weekly 2026-11-09: benzene list prices down 1,500 CNY in four days, ethanol stocks build, European ammonia producer cuts output
11/9/2026
A weekly review of the chemical market: domestic aromatics and alcohol chains weakened in tandem, Europe's nitrogen-fertilizer industry cut output under cost pressure, while new capacity in solar materials, magnet supply chains and bio-based surfactants landed overseas one after another — shifting equipment demand from maintenance-driven to expansion-driven. This digest compiles eight traceable industry updates for capacity planning and equipment selection.
Domestic market: why did pure benzene fall 1,500 CNY/t in four trading days?
### Pure benzene: lower opening, four straight list-price cuts
According to Sci99 market monitoring, the domestic pure benzene market kept falling in the previous session: dragged by weaker crude overnight, night-session prices moved lower, sellers increased offers at the open while buying interest stayed thin. In the afternoon, major refiners cut list prices again, down 1,500 CNY/t cumulatively over four trading days. Sentiment-wise, the market expects November imports and domestic output to rise together; in Shandong, downstream buyers pressed bids hard. A survey shows 70% of players expect prices to hold and 30% expect a further 100-200 CNY/t decline. For refineries and storage operators, inventory rhythm and the safe operation of storage tanks deserve close attention in a falling market.
Source: Sci99
### Ethanol: surplus doubles, stock-building pressure builds
JLC supply-demand data show a domestic ethanol surplus of 32,500 tonnes in October; in November total supply rises 4.61% month on month while total demand slips 1.17%, widening the surplus to 80,500 tonnes. Looking ahead, year-end inventories are forecast to climb from 169,000 tonnes in December to 290,000 tonnes in January. By process, bio-fermented ethanol in the northeast still has order support, while coal-based ethanol stays weak with falling-price risk as some Shandong units plan restarts in mid-to-late November. The market is set to remain under sustained stock-building pressure.
Source: JLC Network
### High-temperature coal tar: how long can a three-week price freeze last?
JLC data show Shanxi Pengfei's coal-tar auction settled at 5,550 CNY/t, flat with last week, and Shanxi and Tangshan have held the same price for three straight weeks. On supply, as of November 6 the operating rate of all sampled independent coking enterprises stood at 70.37%, down 0.75 percentage points, with average per-tonne coking profit at -9 CNY/t, still loss-making. On demand, deep-processing utilization rose 0.20 points to 54.48%, and carbon-black utilization rose 0.7 points to 60%. With bulls and bulls locked in stalemate, a third round of coke price cuts would likely shrink coal-tar supply further.
Source: JLC Network
Overseas market: how deep is the cost squeeze on European ammonia?
AGF Nitrogen, Europe's second-largest ammonia and fertilizer producer owned by Czech agri group Agrofert, said on November 4 that high natural-gas prices and sharply weaker fertilizer demand had forced it to idle part of its ammonia lines: one line in France stopped and another running intermittently, fertilizer plants running at a low 80-85% load, with ammonia now imported. The company runs eight ammonia lines across France, Germany, Slovakia and Austria with annual capacity of 3.5 million tonnes of ammonia and 7 million tonnes of fertilizer, about 20% of the European market; with restart costs of several million euros each time, new investments are paused. For equipment makers serving ammonia, fertilizer and gas-purification plants — including stainless steel reactors — the European cutbacks are both a window to watch and a signal of structural demand change.
Source: PROCESS China
Overseas capacity: where is new solar- and magnet-driven capacity landing?
### Nouryon: MMAO capacity lands in Jiaxing, China
According to Chemical Engineering, Netherlands-based Nouryon will add modified methylaluminoxane (MMAO) capacity at its existing Jiaxing site in China, with production planned to start in the first half of 2028. MMAO is the key activator of catalyst systems for polyolefin elastomers (POE) — the core material of solar encapsulant films and lightweight auto parts. Placing capacity in China means global chemical players are pulling supply chains closer to demand centers.
Source: Chemical Engineering
### Current Chemicals: rare-earth fluoride expansion targets magnet supply chain
The same outlet reported that US-based Current Chemicals received additional investment from its lead shareholder to significantly raise capacity for neodymium fluoride, dysprosium fluoride and other rare-earth fluorides in Cleveland, targeting 1,000 tonnes per year and beyond. Rare-earth fluorides are key feedstocks for converting separated oxides into rare-earth metals and permanent magnets; fluorine-salt media at high temperature place extreme demands on reactor metallurgy and lining, making material selection a core topic for such lines.
Source: Chemical Engineering
Overseas industry: bio-based surfactants scale up, battery anode partnership
### BASF: APG expansion inaugurated in Cincinnati
Renewable Carbon News reported that BASF completed and inaugurated the expansion of alkyl polyglucosides (APG) capacity at its Cincinnati site, strengthening regional supply in North America. APGs combine high performance, mildness and biodegradability for personal-care and household-cleaning formulations; from slurry premixing to final blending, the temperature control and dispersion configuration of emulsifier tanks directly affect batch stability.
Source: Renewable Carbon News
### Stora Enso and Shanshan Technology: lignin hard-carbon anode demo line
Renewable Carbon News also reported a partnership between Stora Enso and Shanshan Technology to build a demonstration line for lignin-based hard-carbon anode materials in Ningbo, China, to industrialize the Lignode technology. Hard-carbon anodes demand strict particle-size distribution and batch consistency; comminution-classification and wet fine-grinding steps with nano sand mills are key equipment topics on the way from demonstration to mass production.
Source: Renewable Carbon News
Further reading: - Chemical Market Weekly 2026-11-08 - How to choose stainless reactor materials
This digest is compiled by Haolin Shengda Equipment Manufacturing Co., Ltd. (hyline.cn); all information belongs to the original authors. Main products: stainless steel reactors, mixing tanks, storage tanks, dispersers, concentration tanks and complete chemical lines, with non-standard customization supported.
Related Products
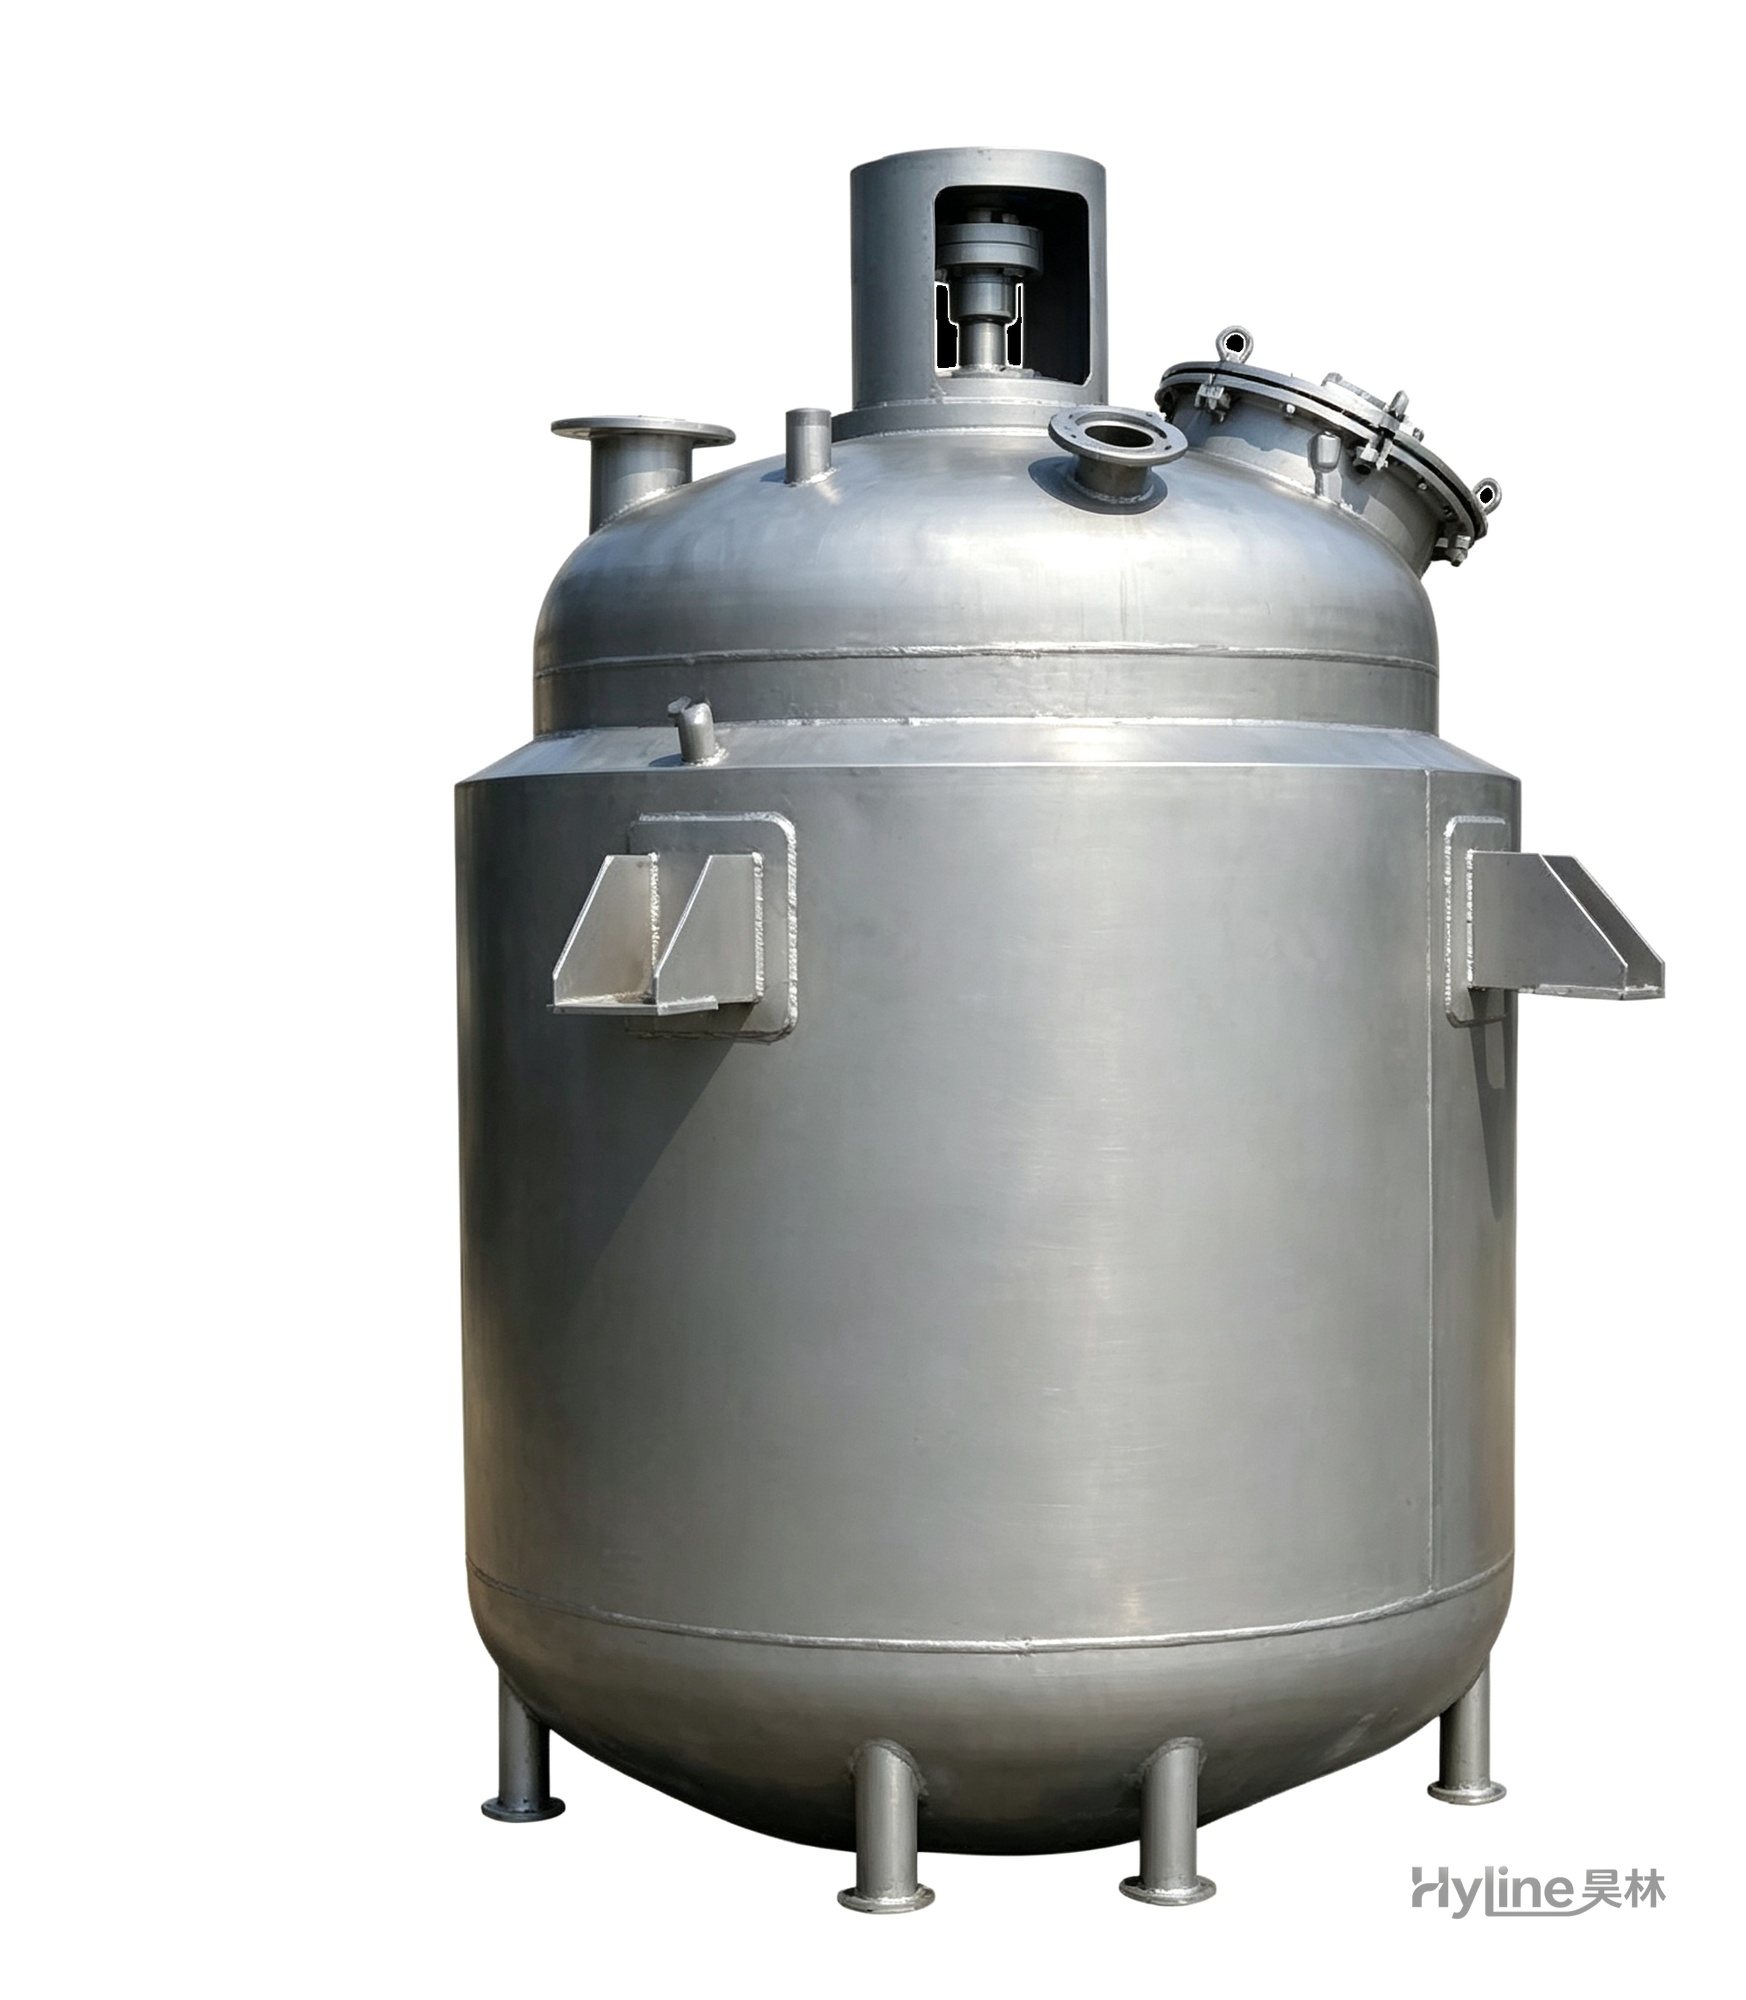
Jacketed Reactor
The typical main reaction vessel in chemical production. Mixing, heating and cooling disperse and mix materials for reaction and polymerization. The jacket circulates thermal oil/steam for heating or cooling water for temperature control.
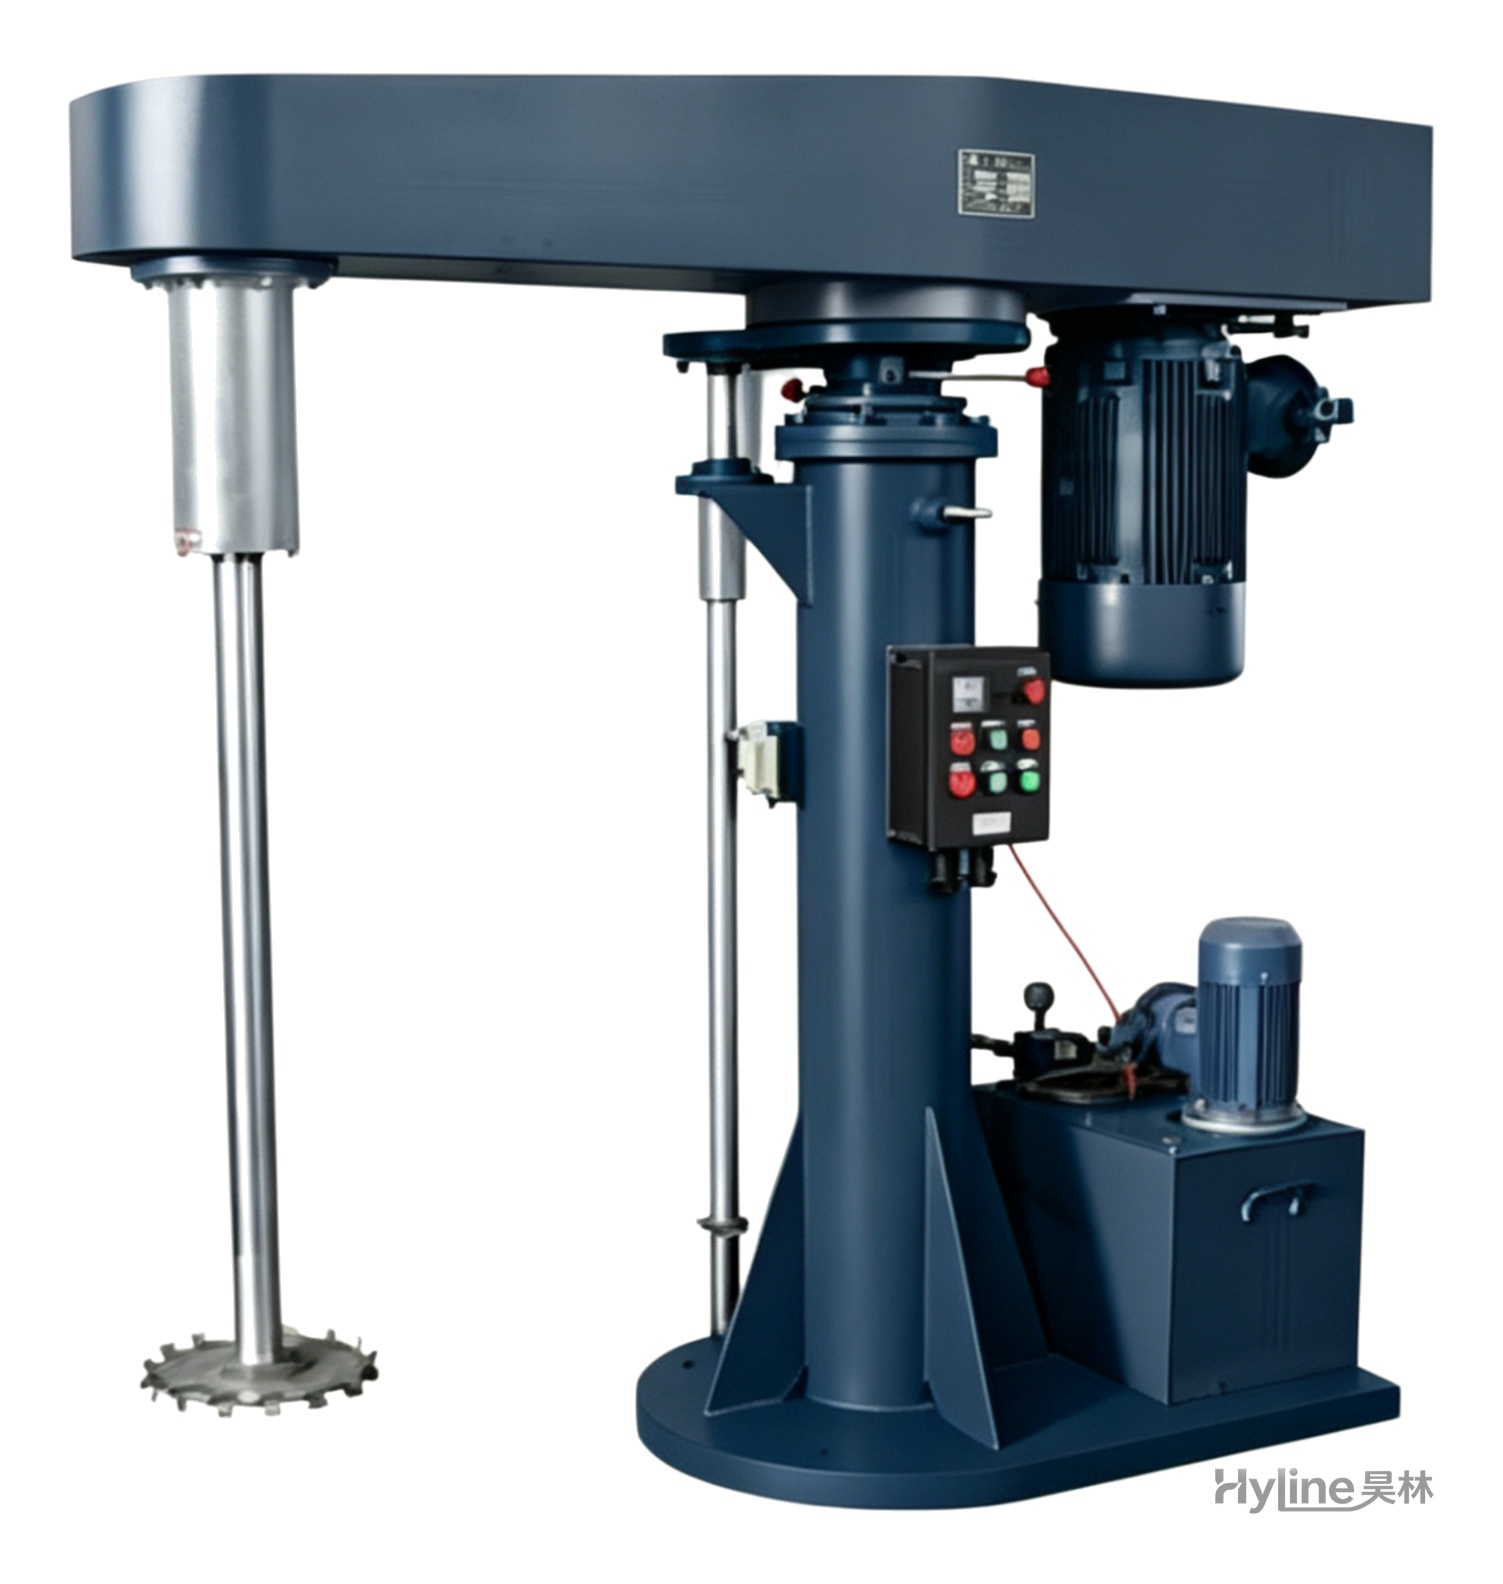
FL Series High-Speed Disperser
Stirs, dissolves and disperses liquids and powders, working alone or matched with sand mills. Variable-frequency drive with hydraulic lift, widely used in paints, inks, coatings, dyestuffs and papermaking.
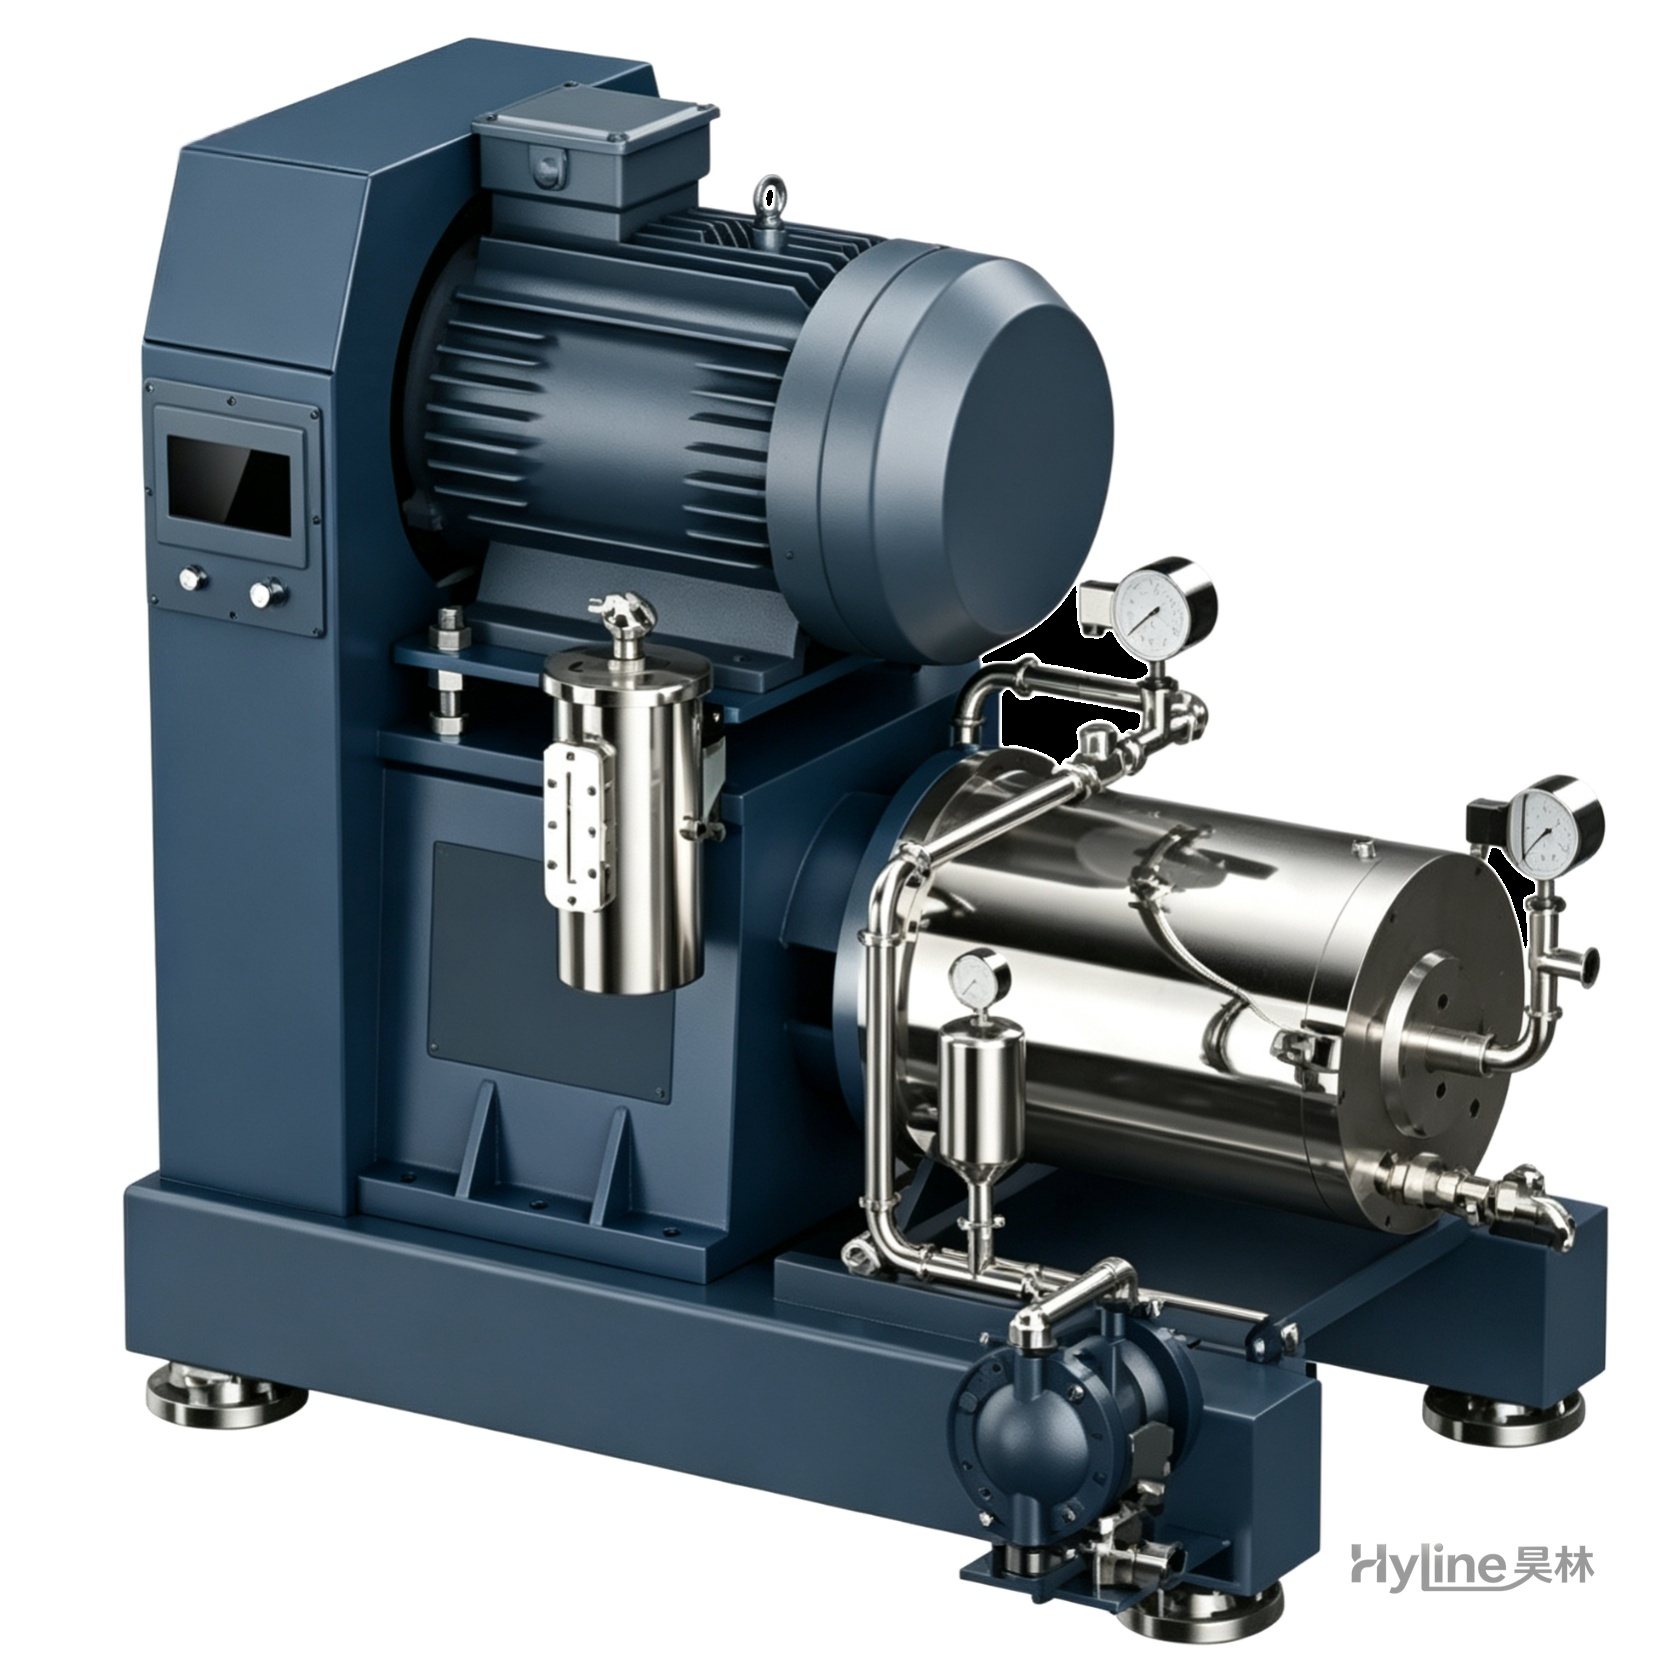
TDB Nano Sand Mill (Rod Pin Type)
Designed to advanced European standards with ample flow, excellent temperature control and high energy efficiency, achieving narrow particle size distribution at nano grade. Widely used in ceramics, inks, lithium battery materials, electronic slurries, nano pastes and pesticides.
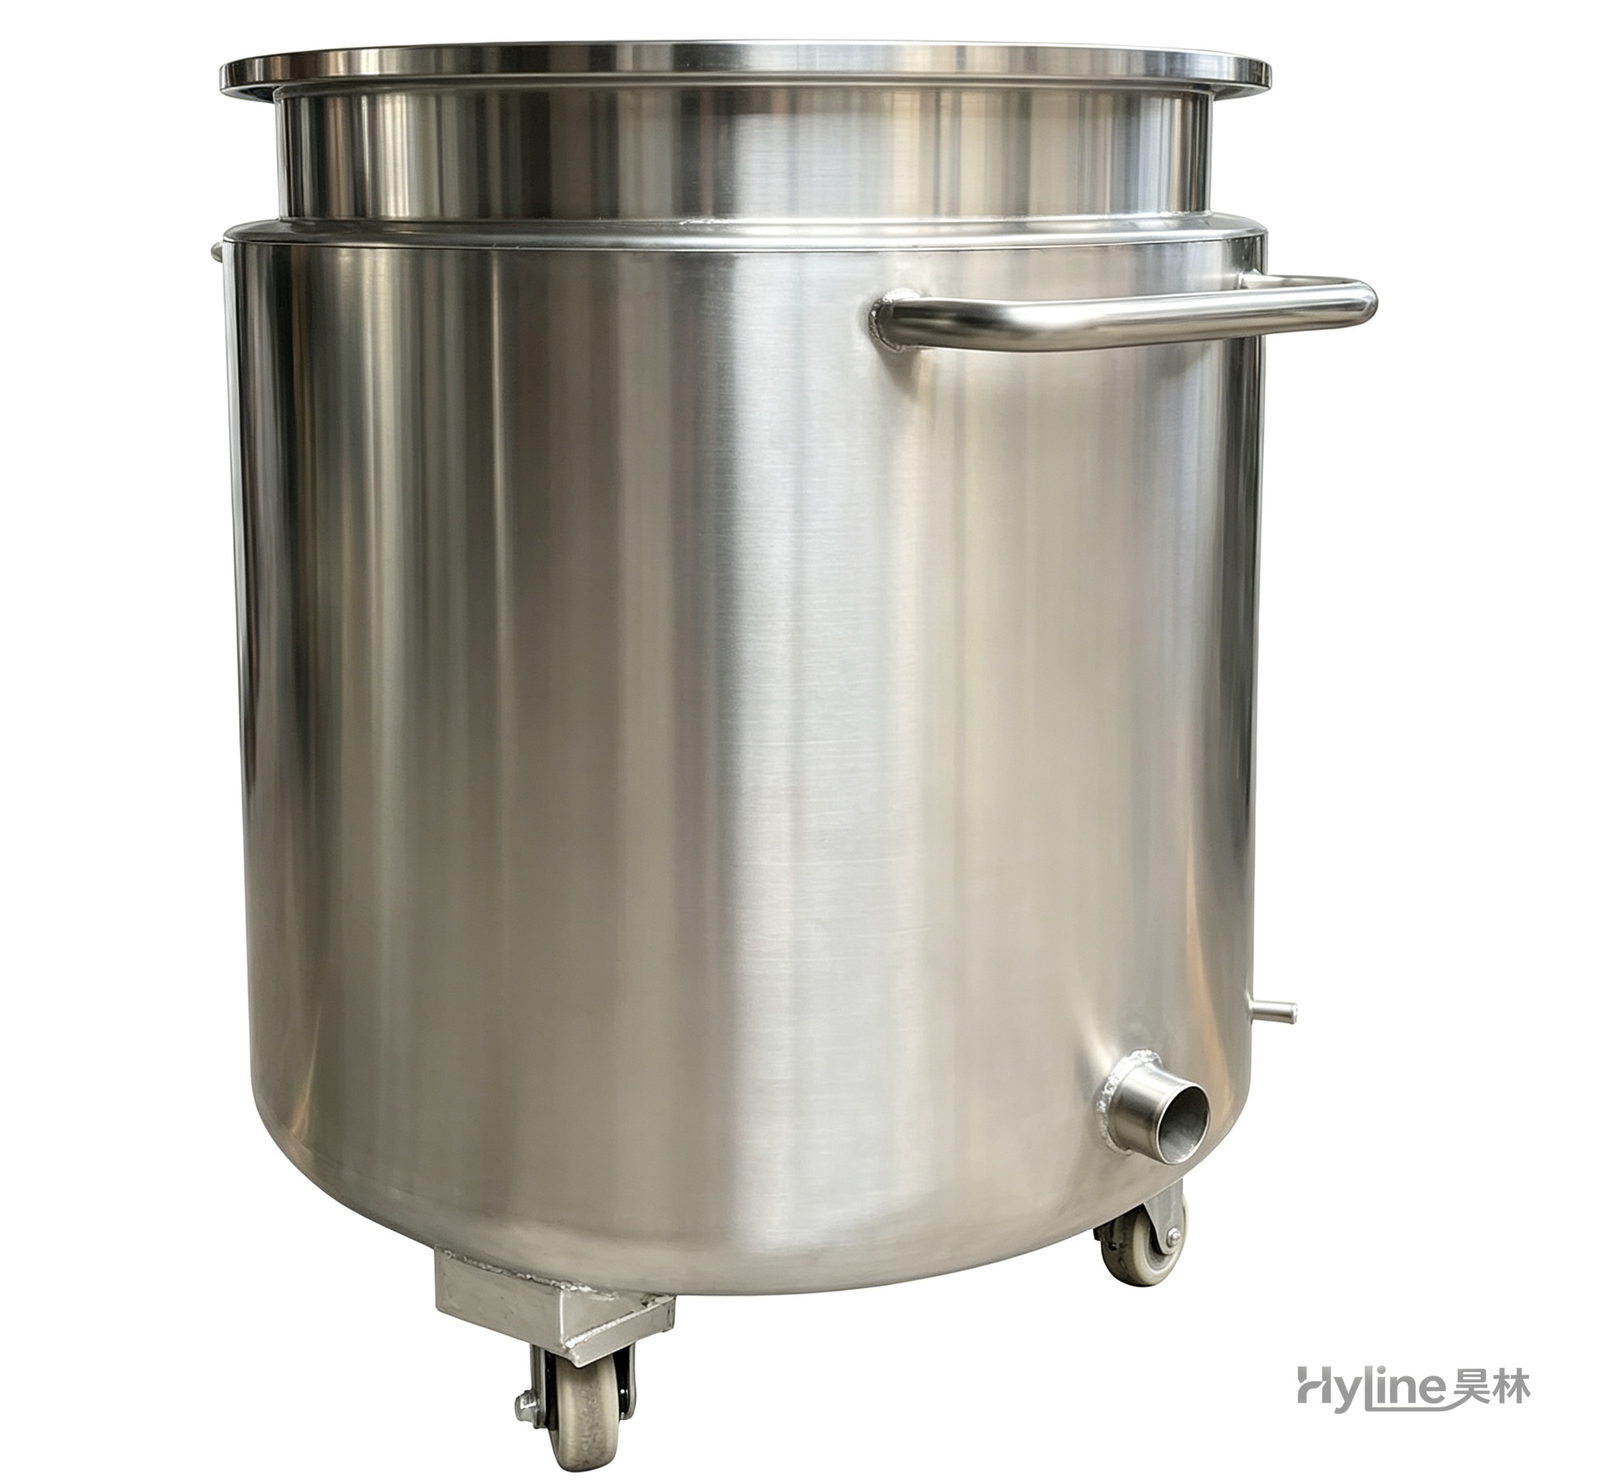
Stainless Steel Mixing Tank (Dispersion Drum)
Supporting vessel for dispersers and mixers in paints, coatings, adhesives, color slurries, inks and electronics. Available in 201/304 stainless with internal/external polishing and sloped bottom side discharge for complete draining.